How Far Back Does a Rental Background Check Go?
Navigating the rental market can feel like an Olympic sport, especially when you're worried about what might pop up on a background check. It's totally natural to feel a knot in your stomach wondering if that old mistake or a past financial hiccup will derail your chances of landing your dream apartment. This comprehensive guide is here to pull back the curtain on how far back a rental background check goes, breaking down what landlords typically look for, the timeframes involved, and how federal and state laws impact what can and cannot be considered.
Understanding the Rental Background Check Process
When you apply for a new apartment, you're essentially handing over your financial and personal history for review. Landlords and property managers aren't just being nosy; they're trying to assess risk. They want to ensure you're a responsible tenant who will pay rent on time, take care of the property, and be a good neighbor. This assessment typically involves a deep dive into several areas, each with its own set of rules and reporting limits.
What Information Do Landlords Look For?
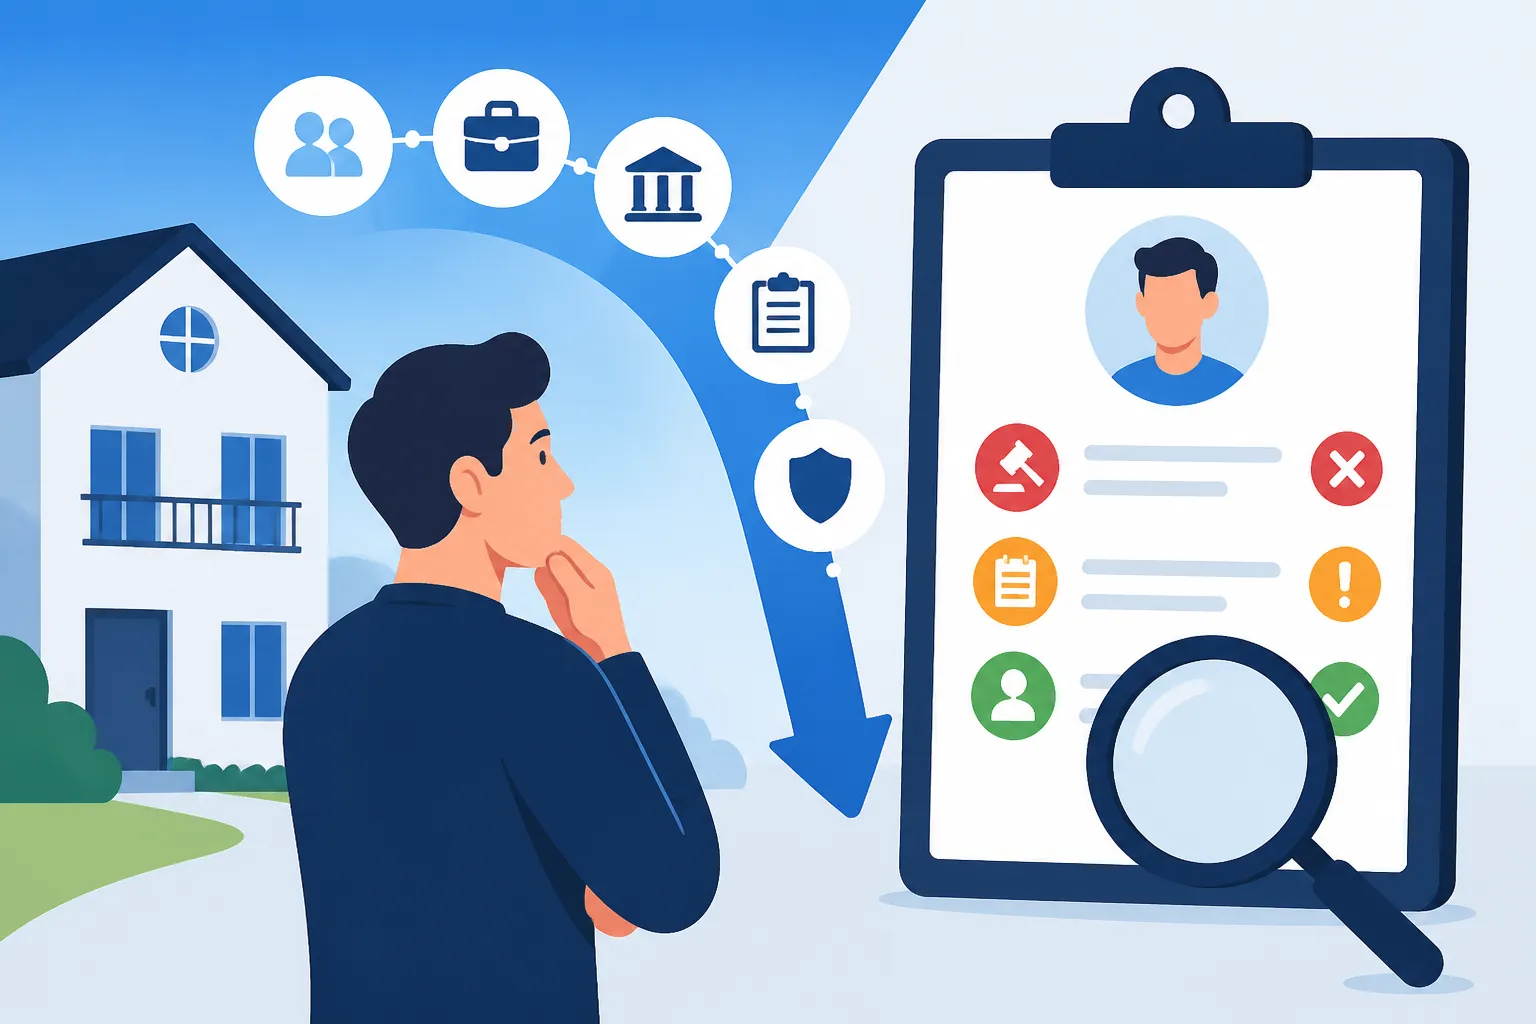
A standard rental background check isn't just one single report; it's usually a combination of checks that paint a full picture of an applicant. Landlords use these reports to gauge reliability and responsibility.
First up is your credit history. This isn't just about your credit score, though that's certainly a factor. It's a detailed look at your payment habits, outstanding debts, and any significant financial events like bankruptcies or collections. Landlords want to see if you have a history of paying your bills consistently, as this is a strong indicator of whether you'll pay your rent on time. A low credit score isn't always an automatic disqualifier, especially if you can explain past issues or show recent improvements, but a pattern of missed payments or high debt can definitely raise a red flag. Services like TurboTenant offer comprehensive credit reports for landlords to review.
Next is your criminal history. This is often one of the most contentious parts of a background check, and it's also an area with significant legal variations. Landlords are typically looking for convictions that might pose a risk to the property, other tenants, or the community. This can include felonies, certain misdemeanors, or crimes involving violence, property damage, or drug manufacturing. However, not all criminal records are treated equally, and the relevance of a conviction to tenancy is a key legal consideration.
Eviction history is another critical component. An eviction filing or judgment against you tells a landlord that you've previously failed to uphold a lease agreement, often due to non-payment of rent or other serious lease violations. This is a massive red flag for landlords, as evictions are costly, time-consuming, and indicate a high-risk tenant. Even an eviction filing that didn't result in a judgment can sometimes show up and cause concern, though many states protect tenants from having dismissed or withdrawn cases appear.
Finally, there's rental history verification. This often involves contacting your previous landlords to ask about your tenancy. They'll inquire about things like whether you paid rent on time, if you caused any damage beyond normal wear and tear, if you had unauthorized occupants or pets, and if you gave proper notice when moving out. This part of the check relies heavily on direct communication rather than databases, making a good relationship with past landlords incredibly valuable.
The Role of FCRA Fair Credit Reporting Act
It's crucial to understand that not just any information can be pulled on a background check, nor can it be kept indefinitely. The federal Fair Credit Reporting Act (FCRA) is the law of the land here, designed to promote the accuracy, fairness, and privacy of information in the files of consumer reporting agencies (CRAs). These are the companies that compile and sell consumer reports, including those used for tenant screening.
Under the FCRA, there are strict rules about what can be reported and for how long. For example, most negative credit information, like late payments, accounts in collection, or foreclosures, generally cannot be reported after seven years. Bankruptcies are a bit different, typically staying on your report for up to ten years. These time limits are designed to give people a chance to recover from past financial difficulties without being perpetually penalized.
The FCRA also grants you certain rights. You have the right to know if information in your file has been used against you, the right to dispute inaccurate or incomplete information, and the right to obtain a free copy of your consumer file. This means if a landlord denies your application based on a background check, they must provide you with an "adverse action notice" that includes the name and contact information of the consumer reporting agency that provided the report. This allows you to review the report and challenge any errors, which is a powerful tool in your corner. Understanding your rights under the FCRA is key to protecting yourself during the application process.
Timeframes for Different Screening Components
The question of "how far back" is not a single answer; it varies depending on the type of information being scrutinized. Each component of a rental background check has different reporting limits, often governed by a combination of federal and state laws.
Credit History Lookback Periods
When a landlord requests a credit report, they are typically looking at your financial behavior over the past several years. As per the FCRA, most negative items on your credit report, like late payments, charge-offs, collection accounts, and paid tax liens, will generally fall off after seven years. This seven-year mark is a standard for many types of adverse financial information.
However, there are a few exceptions. Bankruptcies, for instance, can remain on your credit report for up to ten years, depending on the type of bankruptcy filed. Unpaid tax liens can also remain for much longer, sometimes indefinitely, until they are paid. Civil judgments (like those from a lawsuit) used to be reported for seven years or until the statute of limitations ran out, whichever was longer, but changes to reporting practices mean many major credit bureaus no longer include most civil judgments or paid tax liens on reports. This can be a relief for many applicants.
Landlords aren't usually looking for every single transaction from your past. They're trying to see a pattern of financial responsibility. If you had a few late credit card payments five years ago but have been impeccable since, many landlords will view that more favorably than recent, ongoing issues. The goal for you is to demonstrate current stability, even if your past isn't perfect. If you're wondering what your credit score needs to be to rent, remember that it's just one piece of the puzzle.
Criminal History Lookback Periods
This is where things get really intricate, as criminal history lookback periods vary significantly by state and sometimes even by city. Federally, the FCRA dictates that non-conviction records (like arrests that didn't lead to a conviction) generally cannot be reported after seven years. However, conviction records often have no statutory time limit under the FCRA itself, meaning a conviction could technically be reported indefinitely by some consumer reporting agencies.
This federal leeway has led many states to implement their own, more restrictive laws. For example:
- In California, some older conviction records may not be reported or considered, especially for certain types of offenses, with varying lookback periods (e.g., 7 years for some misdemeanor convictions, longer for felonies).
- New York has laws that prevent landlords from inquiring about or acting upon certain older criminal convictions, and they cannot consider non-felony convictions after a certain period (often 7 years).
- In Washington state, there are limits on how far back a landlord can look for criminal history, often restricting it to the past seven years for most offenses.
- Many states have "ban the box" laws that prevent landlords from asking about criminal history on the initial application, pushing that inquiry to later in the process.
Beyond state laws, the Department of Housing and Urban Development (HUD) has issued guidance emphasizing that blanket exclusions of applicants with criminal records can lead to disparate impact discrimination against protected classes under the Fair Housing Act. This means landlords must have a legitimate business reason for their criminal screening policies and consider factors like the nature and severity of the crime, how recently it occurred, and evidence of rehabilitation. For more detail on what a landlord can and cannot ask, especially concerning criminal history, it's worth reviewing local regulations.
Eviction History Lookback Periods
Eviction records are generally reported on tenant screening reports for seven years. This includes both eviction filings that resulted in a judgment against the tenant and, in some cases, even filings that were dismissed or withdrawn. The exact details depend on the specific reporting agency and state laws.
An eviction judgment is a public record, meaning it's readily accessible and will almost certainly appear on a background check for the full seven-year period. Some states have moved to seal eviction records that did not result in a judgment or where the tenant prevailed, but this isn't universal. This is why having an eviction on your record can be one of the toughest hurdles to overcome when trying to rent, potentially even more so than bad credit, because it directly speaks to your reliability as a tenant. You can find more specific information about the eviction process by state if you're concerned about past or potential issues.
Rental History Verification
Unlike credit or criminal checks, there isn't a strict "lookback period" for rental history verification in the same way. Landlords typically contact your most recent two or three landlords to get references. They're interested in your behavior during your last few tenancies.
This doesn't mean your entire rental history is irrelevant; if you've been a tenant for twenty years, a landlord isn't going to call every single landlord you've ever had. They focus on recent and relevant experience. If you had a problem with a landlord seven years ago, but have had two positive tenancies since, the more recent positive experiences will likely outweigh the older issue. However, if a previous landlord gives a negative reference, especially for issues like property damage or repeated late payments, it can certainly impact your application, even if it's from a few years back. The key here is proactive communication and ensuring your most recent rental experiences are solid.
State-Specific Nuances and Regulations
It's impossible to talk about rental background checks without diving into state-specific laws, as these can drastically alter what a landlord can consider and for how long. While the FCRA sets a federal baseline, many states and even individual cities have enacted their own, often more tenant-friendly, regulations.
States with Stricter Background Check Rules
Several states and municipalities have recognized the impact of lengthy background checks on housing accessibility and have implemented stricter rules. These regulations aim to give tenants a fairer shot, especially those with past issues that are no longer relevant to their current ability to be a good tenant.
For instance, states like California are often at the forefront of tenant protections. In California, there are rules that limit how far back a landlord can inquire about certain types of criminal convictions or older debts. Additionally, cities within California, such as San Francisco, have even more stringent laws, sometimes prohibiting landlords from considering certain criminal convictions or requiring a more individualized assessment rather than a blanket denial. These laws are designed to help people re-enter the housing market without being perpetually penalized for past mistakes. If you have questions like "Can a landlord deny you for a criminal record?" or "Can a landlord deny you for bad credit?", understanding your state and local laws is paramount.
New York is another state that offers significant tenant protections. Specific to criminal history, New York generally restricts the use of certain older convictions and non-felony offenses in housing decisions. Their laws, especially in New York City, often emphasize the need for landlords to consider the individual circumstances of an applicant's criminal history, rather than automatically denying them.
Washington state has also implemented laws to limit the lookback period for criminal convictions in housing applications, typically to seven years for most offenses. These regulations are a clear effort to balance a landlord's need to screen tenants with a tenant's right to housing opportunities.
These examples highlight a growing trend: states and cities are moving towards more nuanced approaches to tenant screening, recognizing that a person's distant past doesn't always reflect their current reliability. This is where companies providing screening services, like TurboTenant, must stay constantly updated on these varying laws to ensure compliance for landlords.
How HUD Guidance Impacts Criminal Screening
Beyond state laws, the Department of Housing and Urban Development (HUD) has provided crucial guidance on the use of criminal records by housing providers. While not a law itself, HUD's guidance interprets the Fair Housing Act and explains how certain screening practices could lead to discriminatory outcomes.
HUD's primary concern is "disparate impact." This means that even if a landlord's policy seems neutral on the surface (like "no applicants with any criminal history"), if it disproportionately affects individuals of a certain race, color, national origin, religion, sex, familial status, or disability, it could be considered discriminatory. This is particularly relevant for criminal records because, due to historical systemic issues, certain racial and ethnic groups are disproportionately arrested, convicted, and incarcerated.
Therefore, HUD recommends that landlords avoid blanket bans on applicants with any criminal record. Instead, they should:
- Prove a "Substantial, Legitimate, Nondiscriminatory Interest": The landlord must show that their policy is necessary to protect resident safety or property.
- Consider the Nature and Severity of the Crime: A landlord should assess the type of crime (e.g., violent vs. minor drug offense) and its potential impact on the community.
- Consider the Time Since the Conviction: How long ago did the crime occur? A conviction from 20 years ago might be less relevant than one from last year.
- Consider Evidence of Rehabilitation: Has the applicant demonstrated efforts to turn their life around? This could include educational achievements, stable employment, or participation in rehabilitation programs.
This guidance forces landlords to move beyond simple "yes/no" answers based on criminal records and instead engage in a more individualized assessment. If you've been denied an apartment and suspect it was due to an old criminal record without proper consideration, you may have grounds to dispute it, especially if the landlord didn't adhere to HUD's principles. For landlords, understanding the Fair Housing Act: protected classes explained is critical to avoid legal pitfalls.
What to Do If You Have Concerns About Your Background
It's completely normal to feel anxious if you know there's something in your past that might appear on a rental background check. The good news is that you're not powerless. Being proactive and informed can significantly improve your chances of securing housing.
Being Transparent with Potential Landlords
One of the most effective strategies is often simple honesty. If you have an issue in your past – an eviction, a bankruptcy, or a criminal record – it's usually better to address it head-on with a potential landlord rather than waiting for them to discover it and form their own conclusions. Think of it as controlling the narrative.
When you submit your rental application, or even during an initial conversation, you can subtly bring up your concern. For example, if you had an eviction five years ago due to a job loss, you could say, "I wanted to let you know upfront that about five years ago, I went through a rough patch and had an eviction filing due to unemployment. Since then, I've secured stable employment at [Your Company Name], and I've been diligent about my finances, as you'll see from my recent payment history. I'm happy to provide additional references or proof of income."
This approach shows maturity, responsibility, and transparency. It gives you a chance to explain the circumstances, demonstrate how you've learned and grown, and highlight your current stability. Many landlords appreciate this candor, especially if you can back up your words with solid proof of improved financial habits, a stable job, or positive references from employers or more recent landlords. Remember, a good landlord is looking for a reliable tenant, and sometimes an honest explanation can bridge the gap left by a past record. This is a key step to consider if you're trying to figure out how to get approved for an apartment with bad credit or a difficult rental history.
Understanding Your Rights and Disputing Errors
Another crucial step is to know your rights and regularly check your own reports. You have the right to request a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once every 12 months. This allows you to see exactly what landlords will see, and more importantly, to identify any inaccuracies.
Under the FCRA, if you find errors on your credit or tenant screening report, you have the right to dispute them with the reporting agency. They are legally required to investigate your dispute, usually within 30 days, and correct any inaccurate or incomplete information. This process can make a real difference, as removing incorrect negative items can significantly improve your profile. You can also dispute incorrect information directly with the original source of the information (e.g., a past landlord, a collection agency).
If a landlord denies your application based on information in a background check, they are obligated to send you an adverse action notice. This notice will tell you which consumer reporting agency provided the report, and you can then request a free copy of that specific report to review. This is your chance to ensure everything is accurate and, if not, to take action. Ignoring these notices or failing to check your reports means you might be penalized for information that is wrong or should have been removed.
Building a strong case for yourself often means having all your ducks in a row: gathering positive references, providing proof of income, and even obtaining your own tenant screening report to ensure it's accurate before you even apply. These proactive steps can alleviate much of the stress and give you a better chance at securing your next home.
Summary of Typical Background Check Lookback Periods
Here's a quick overview of common lookback periods for rental background checks:
| Component | Typical Lookback Period | Notes |
|---|---|---|
| Credit History | 7 years | Most negative items (late payments, collections, charge-offs). Bankruptcies up to 10 years. Unpaid tax liens may stay longer. Some older civil judgments and paid tax liens are no longer reported by major bureaus. |
| Criminal History | Varies by State | Federally, non-convictions (arrests not leading to conviction) ~7 years. Convictions can technically be indefinite under FCRA, but many states (e.g., CA, NY, WA) limit reporting to 7 years or have specific rules based on the crime's severity and age. HUD guidance impacts. |
| Eviction History | 7 years | Eviction filings and judgments typically remain on reports for 7 years. Some states may seal records for cases not resulting in a judgment. |
| Rental History | Recent 2-3 landlords | No strict legal lookback. Landlords typically contact most recent landlords to verify payment, property care, and tenancy behavior. |
Remember, these are general guidelines, and specific state and local laws can always alter these timeframes.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.